 DEV
The unwind, in sequence
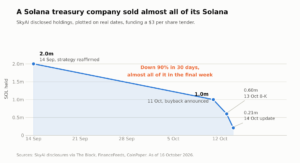
Chart 1. Plotted on real dates, which is the point: three of the four disclosures fall inside four days. Sources: SkyAI disclosures via The Block, FinanceFeeds, CoinPaper.
Three filings in four days took the treasury from roughly half sold to almost entirely sold. That is close to 90 per cent in a month, from a company whose stated purpose was accumulating it.
The governance fight
Bastion Trading called the sales a fundamental departure from the strategy and asked for dates, quantities, prices, proceeds and how each transaction was approved. It wants the tender raised to at least $3.50 and advisor warrants excluded.
The pressure is not new. At a September shareholder meeting, all five SkyAI directors drew more votes against than for. The company has also rejected an acquisition approach from Forward Industries, the larger Solana treasury firm, saying it undervalued SkyAI.
The tender was expected to open around 15 October and run ten business days, which gives this story a defined second beat.
The other direction
Strive went the opposite way in the same week, and the contrast is the piece.
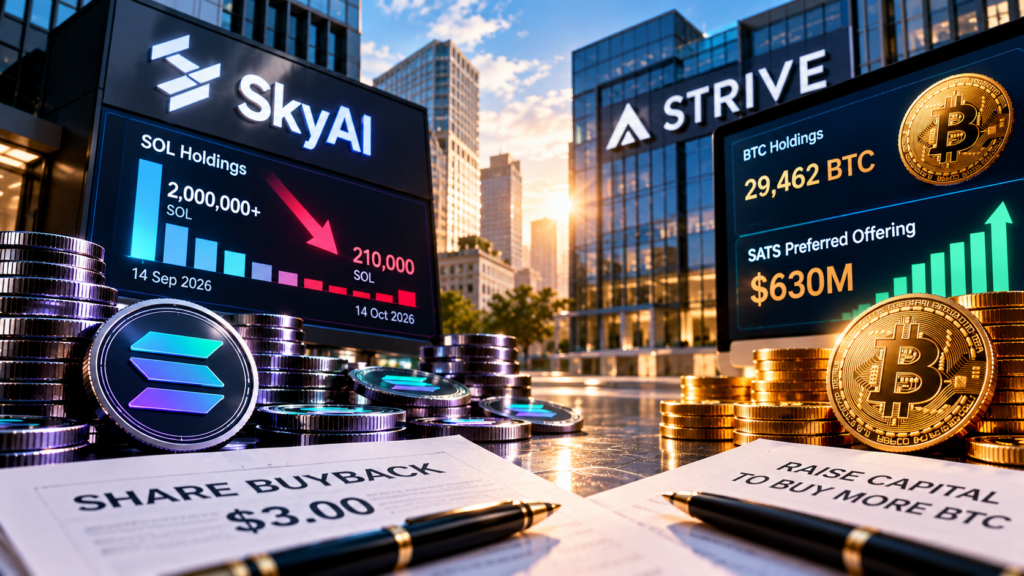
On 13 October it launched a SATS perpetual preferred offering, then upsized it to 7 million shares priced at $90, a 10 per cent discount to face, for about $630m gross. The $15 annual dividend works out at a 16.67 per cent yield at the offer price. Settlement is set for 20 October.
The balance sheet behind it: 29,462 BTC as of 2 October per its 8-K, bought at an average cost near $90,170, against bitcoin trading around $81,000. The company’s own investor materials put the treasury break-even, the return needed to cover all SATA and SATS dividends, at 7.2 per cent a year.
So one treasury company is liquidating to buy back its own equity at a discount, and another is issuing high-yield preferred at a discount to buy more. Both are responses to the same condition: the shares are worth less than the coins.
The frame for the piece
The 2025 treasury-company thesis was that a listed wrapper trades at a premium to its holdings, so issuing equity to buy more coins is accretive per share. When the premium inverts, the machine runs backwards. Buying back stock below NAV is the rational move, and it means selling the asset.
Six listed companies hold roughly 17 million SOL, about 2.9 per cent of circulating supply. If the discount persists, SkyAI is a template rather than an outlier.
Comments (0)
No comments yet. Be the first to share your feedback below!
Leave a Feedback
We'd love to hear your thoughts on this article.