 DEV
The number the market had not priced
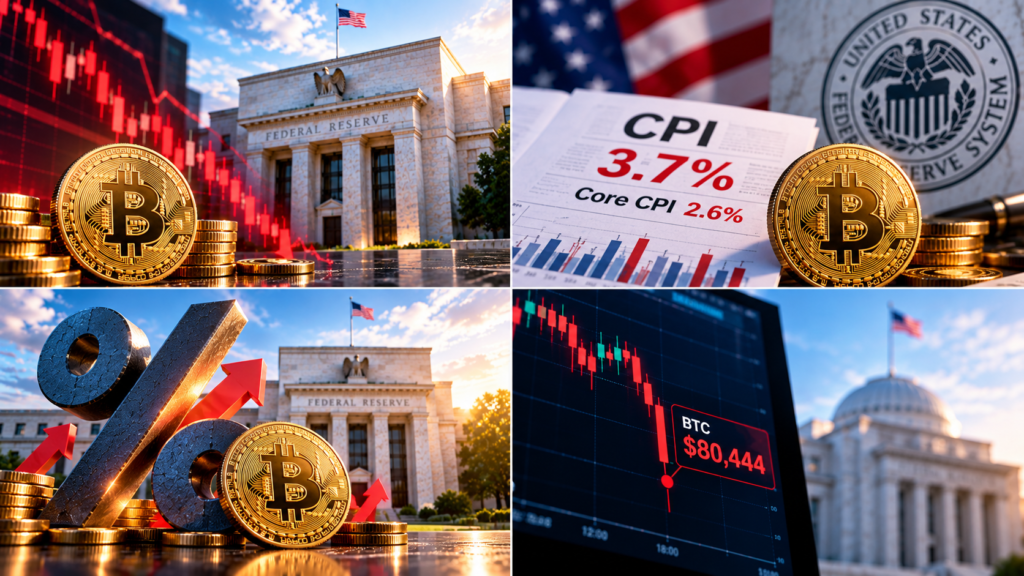
The Bureau of Labor Statistics released September CPI at 12:30 UTC on Wednesday 14 October. Headline came in at 3.7 per cent against a 3.6 per cent forecast. Core, excluding food and energy, rose 0.3 per cent on the month and 2.6 per cent on the year, after 2.4 per cent through August.
That acceleration in core is the part that matters. Headline can be argued away with oil. Core reversing direction cannot.
BREAKING: September CPI inflation rises to 3.7%, above expectations of 3.6%
Core CPI inflation rises to 2.6%, also above expectations of 2.5%.
This officially marks the third highest US inflation reading since September 2023.
Rate hike expectations are rising on the news.
— The Kobeissi Letter (@KobeissiLetter) October 14, 2026
Why this is a different regime, not a different week
The Fed already hiked. On 16 September the FOMC voted 12 to 0 to raise the target range by 25 basis points to 3.75 to 4.00 per cent, the first increase since July 2023 and the first policy move under chair Kevin Warsh, who took office in May. The median projection put the funds rate at 4.1 per cent at the end of both 2026 and 2027, implying one more move this year. Minutes released 7 October said most participants expected another increase would likely be appropriate by year end.
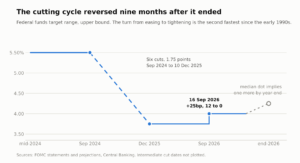
That is the frame for everything below. The cycle turned nine months after the last cut, the second-fastest reversal from easing to tightening since the early 1990s.
What it did to price
Bitcoin fell below $82,000 on Wednesday, then below $81,000 during Asian hours on Thursday, touching an intraday low of $80,444, per CoinGecko. Ether dropped roughly 6.5 per cent to $2,353.
This was not a crypto-only move. South Korea’s Kospi lost 8 per cent and Japan’s Nikkei 225 fell 5 per cent in Thursday morning trading, with an AI capex selloff running underneath. Gold went the other way, reclaiming $4,150.
Spot bitcoin ETFs took $150.5m of outflows on 14 October, reversing a $175.7m inflow the day before. October flows had already flipped from a $321.4m surplus after 6 October to roughly a $452m deficit by 12 October.
The honest read
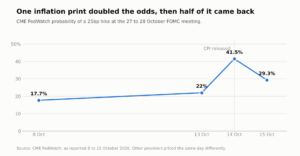
Two things are true and the piece should hold both. The hike is not priced as a done deal: CME FedWatch sat near 29 per cent on Thursday, and most desks still expect a hold in October. But Polymarket traders put a December hike at 79 per cent. The question is timing, not direction.
Avoid predicting a level. The usable line is that the macro assumption underneath the cycle has inverted, and positioning has not caught up.
Comments (0)
No comments yet. Be the first to share your feedback below!
Leave a Feedback
We'd love to hear your thoughts on this article.