 DEV
The defense
Mansour’s argument is that an insider on a prediction market leaves a public record. The Block reported his line about committing a crime in broad daylight. Kalshi says it ran more than 150 investigations and blocked over 100 insider-trading attempts in the first quarter of 2026 alone, and has added employer disclosures in higher-risk markets.
He has reason to make the case. Two episodes are driving the scrutiny.
| Case | What happened | Outcome |
| George Santos | Traded contracts on his own attendance at the State of the Union | Permanently banned by Kalshi; CFTC charged market manipulation rather than insider trading, with a three-year trading ban |
| White House teleprompter operator | Traded on advance access to official speeches | Settled for $172,539 |
A serving Army soldier betting on future military action is also reported to be under scrutiny. Representative Ritchie Torres has a bill that would make it illegal for government officials to trade on inside information in these markets, and Kalshi has said it supports that.
The contradiction
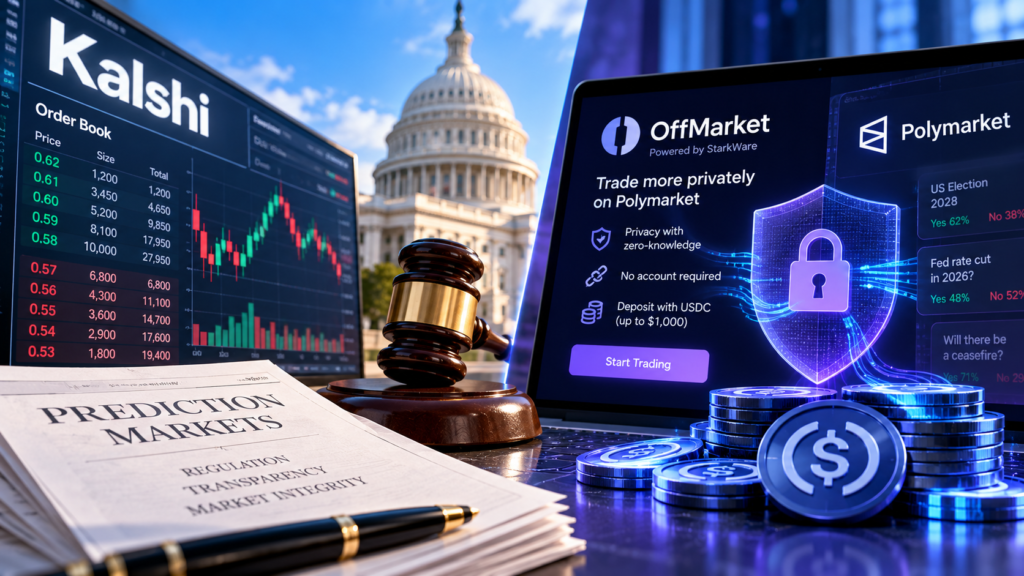
StarkWare’s OffMarket went public on 14 October after a limited release in August. Traders deposit USDC on Polygon and trade Polymarket’s order books without opening a Polymarket account, with a zero-knowledge privacy pool breaking the link between the depositing account and the trading wallet. StarkWare frames it as a VPN for Polymarket.
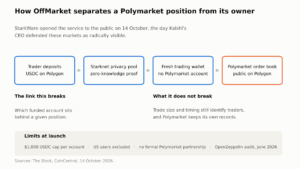
Chart 1. What the service separates, and what it leaves exactly where it was. Sources: The Block, CoinCentral, 14 October 2026
The guardrails are real and worth stating plainly. Deposits are capped at $1,000 USDC per account. OpenZeppelin audited the pool contract in June with no critical or high-severity findings. OffMarket applies Polymarket’s geographic restrictions, so US users are excluded. StarkWare’s own spokesperson said the system cannot stop someone being identified through trade size or timing, and Polymarket keeps its records regardless. It is not a Polymarket product and there is no formal partnership, though it sits in the verified builder programme.
Still, the week’s two headlines point in opposite directions. The industry’s regulatory defence rests on the premise that these markets are radically visible. A funded, audited privacy layer for the largest of them shipped the same day.
Where to take it
This is a reported piece rather than a reaction. The questions worth putting:
- Does Polymarket consider OffMarket compatible with its own surveillance commitments? StarkWare said the platform was aware and content, but had not discussed the launch specifically.
- Does the $1,000 cap stay? StarkWare has said it will adjust limits with demand.
- If the Torres bill passes, how would enforcement work against positions routed through a privacy pool?
The parallel jurisdictional fight is the backdrop: Kalshi and the CFTC say federal law covers event contracts, while multiple states are suing over gaming and sports-betting statutes, and the appeals courts are split. Mansour’s framing is that the real question is whether these markets exist onshore at all.
Comments (0)
No comments yet. Be the first to share your feedback below!
Leave a Feedback
We'd love to hear your thoughts on this article.