 AdminCryptominds
The treasury model only runs in one direction
The listed crypto holder works as a machine with a single gear. While the stock trades above the value of the coins on the balance sheet, the company can issue equity into that premium, buy more coins and justify the premium all over again.
Galaxy Digital’s reading was that this was never a Bitcoin strategy but a liquidity derivative, one that functions only while the equity trades above the underlying. That condition has not held for months.
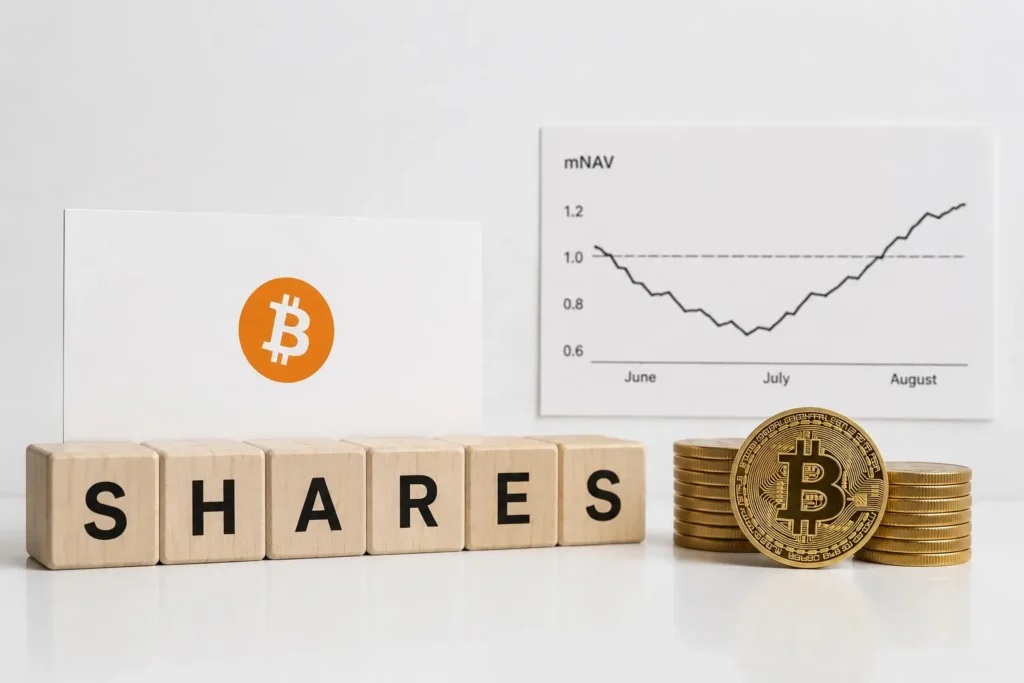
The measure is mNAV, the ratio of market value to the value of crypto held. On 26 June 2026 Strategy’s enterprise mNAV closed below 1.0 for the first time, on figures published on its own site.
What Strategy actually did in August
Between 10 and 16 August the company sold 3,458,866 of its own shares for about $333.7m. It neither bought nor sold Bitcoin in that window.
Of the net proceeds, $52.4m funded dividends on the STRC preferred, $132.2m funded repurchases of the same instrument, and $149.1m went into the dollar reserve, lifting it to $4.8bn.

The following week the pace picked up. An SEC filing shows 18.26 million shares sold between 17 and 23 August for roughly $2bn, about 1.43 million STRC preferred shares bought back for $136.4m, and a further $300m added to the reserve.
The Bitcoin position held at 840,447 BTC, worth around $53.4bn. Average cost sits at $75,385 per coin, for a total outlay of roughly $63.4bn including fees.
Four sales and a promise that did not survive
August falls inside a year in which Strategy has sold Bitcoin four separate times, according to Wall Street Journal reporting on its filings. The most recent was 1,690 BTC for about $108.6m on 10 August.
Michael Saylor spent years saying the company would not sell. A second pledge, made on 31 July 2025, not to issue shares below an mNAV of 2.5, has also gone, on an audit by Protos, of every weekly disclosure since.
The reason for the equity sales sits in the cost base. Preferred dividends alone cost $230m in the first quarter of 2026 and now annualise tonearlyo $1.763bn.
Those payments come due regardless of where Bitcoin trades. While the equity window stays open, they can be funded by issuance, and when it shuts, the coins themselves are the remaining source.
Concentration makes the issue a sector problem rather than a company one. Strategy holds roughly 76 per cent of all Bitcoin sitting on treasury-company balance sheets, which turns its financing decisions into a market-structure variable.
BitMine is running a different book
The largest Ether holder looks very different from its Bitcoin counterpart. As of 23 August BitMine held about 5.85 million ETH, roughly 4.8 percent of supply, alongside $308m in cash and marketable securities.
The company says it never fully stopped buying and added another 32,447 ETH in the preceding week. Earlier in the year, it traded at an mNAV of 0.97, but it carried no debt.
Late August has shifted the starting position again. Strategy’s enterprise mNAV stood at 1.04 in mid-August, and the dollar reserve has grown to $5.1bn, of which roughly $1.6bn counts as flexible.
Sources
- The Block, 17 August 2026
- Investing News Network, 24 August 2026
- Wall Street Journal via Startup Fortune, August 2026
- Protos, 21 July 2026
- Crypto Impact Hub, August 2026
- The Wolf Den, 28 August 2026
Comments (0)
No comments yet. Be the first to share your feedback below!
Leave a Feedback
We'd love to hear your thoughts on this article.